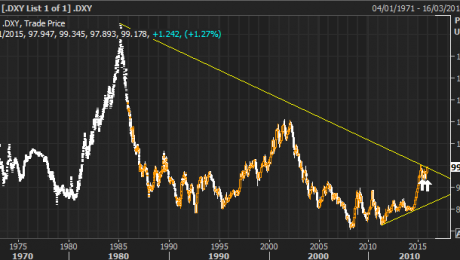
The dollar jumped against a basket of major currencies, pushing oil and gold lower, and short-term U.S. bond yields advanced after strong U.S. jobs data bolstered expectations that the Federal Reserve will raise interest rates in December. Indexes ended modestly higher as a drop in utilities was countered by gains in financial shares.
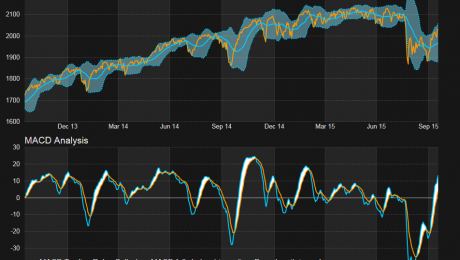
Stocks appear to be on the verge of breaking through the resistance that has defined the equity market since the mid-August swoon. But if that’s going to happen, it’s going to have to come as a result of earnings, with a number of big-name stocks such as Alphabet, AT&T, Microsoft, Caterpillar set to release results.
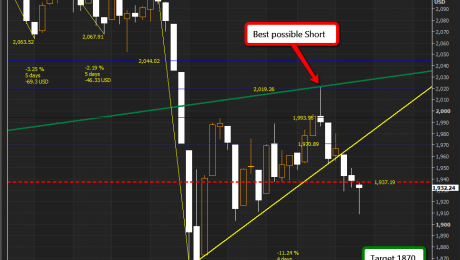
The $SPX still trading in the weak side pushing to lower low on the week. On the other hand, today we had buying pressure MTD the Nasdaq, SP500 and Dow are positive while Europe is negative. The algo are configure to trade mostly to the short side Lingering global growth concerns pushed stocks lower, while
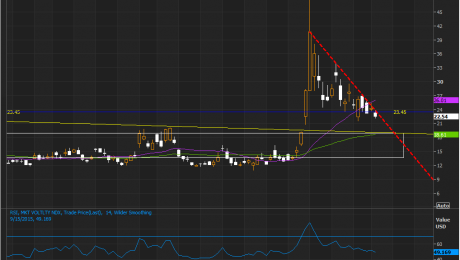
The VIX trader lower increasing the possibility of trading below 21 this week. Upbeat U.S. retail sales data pushed stocks and the dollar higher. Treasuries and gold declined as investors lose appetite for safe-haven assets. Brent was steady ahead of the front-month contract’s expiry, while U.S. oil jumped.
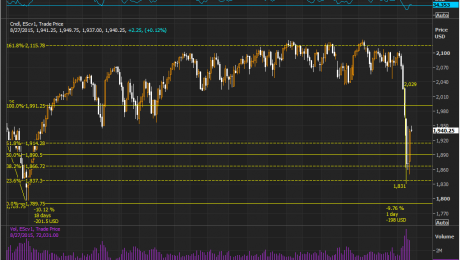
News again for oversees: China eyes near-term yuan stability after devaluation-sources Devaluation sparks outflows, fears of competitive moves C.bank seen now trying to stop yuan weakening past 6.5/dlr China may allow yuan to weaken over time as economy slows SPX Futures, there are more than 100 points to recover.