Fed Likely To Delay, But Meeting Remains Live
The September Fed commentary will be publishing on the 17th this week. We have based our trades on the first rate hike this year. At this point we believe it is more likely that the Fed will use the December meeting to first raise rates. This is due to the potential for deflationary pressures based on commodities prices, China slowdown and global inflation.
Overall monetary policy still remains highly accommodative, with or without a rate hike, which is likely to continue to support both the economy and the stock market going forward. Therefore we continue to hold the view that the Fed will hike this year and will continue to base our trading plan on this.

US Equities
A hike by the Fed this week will likely have a negative effect on US stocks. This is because the market is already concerned about deflationary risks and a rate hike will likely increase these. Should this occur we will look to increase our long exposure as we believe that over the longer term. However, a delay of the rate hike from this week will likely see equities rally as monetary policy will remain loose for longer. This will increase the likelihood that the current deflationary risks will pass without having an effect on the economy and that market concerns will fall leading equities to rally in the near term. This move higher would likely be maintained with stocks rallying over the coming months as accommodative monetary policy would continue to support equities.
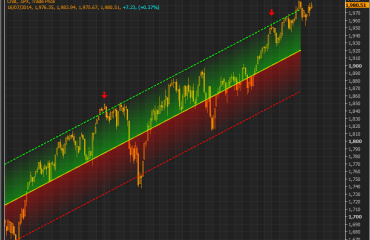
The bullish MACD crossover indicates that stocks have shifted back to bullish movement. This means that if the Fed chooses to delay the resistance at 1990 will likely be broken and the S&P will rally higher towards its previous highs.
I believe that this is the most likely outcome this week, so we are content to continue holding our long trades on the S&P.
Following the Fed meeting we may look to increase our short volatility and long equities exposure. We may also look to add to our gold short trades following the meeting if the metal rallies.
Volatility
If the VIX spikes following the Fed meeting this week we will look to increase our short exposure again. However, if the Fed does not hike then it is likely volatility will fall back further. In this case we will simply continue to hold our XIV positions until the VIX falls close to 15 where we will look to take profits.

European Equities
Monetary policy from the ECB remains highly accommodative. This means that any negative impact from the Fed meeting this week that the US equity markets see is likely to be significantly lessened in Europe. However, if the deflationary risks pass as we believe that they will, the European equity markets are still likely to rally higher over the long term due to the bullish effects on ECB QE.

If this is the case, the negative effect on European stocks over the long term of the Fed hiking rates is likely to be minimal as US monetary policy and that of other central banks globally would still be highly accommodative. Therefore the long term effects of a rate hike would likely be insignificant.
The positive impact of the Fed delaying the first rate hike is likely to flow through to the EURO STOXX 50. Following this the index would likely continue to rally as the bullish effects of ECB QE would push equities higher without selling around fears of deflation counteracting this.