Today’s Retail Sales Report for April showed a top line improvement of 1.3%. Subtracting sales of autos and gasoline it was up .6%. This will have a positive effect of .9% (annualized) on GDP. This followed a .3% decline in March. These are not bad numbers but they are not great either.
The housing market has been strong with few homeowners in most markets having negative equity in their homes. Mortgage default rates are very low now.
Some of the best names in retail have bombed their earnings over the last three days: Macys, Kohls, GAP, Dillard’s and Nordstrom. The shift of sales to the internet was evident in the Retail Sales Report today with in-store sales flat and internet sales up 2% (annualized). However, in-store sales are still 85.3%% of all retail sales (including gasoline and autos).
Recent stronger oil prices have helped the 12.7% of the economy that is directly tied to oil and the 11.3% of the economy that is indirectly tied to oil by manufacturing things, some of which the oil businesses buy. The wind down of the huge Fort McMurray fire in Canada should put a million barrels of oil per day back on the market, which will pressure oil prices down.
Last week the Jobs Report showed a significant deceleration in job growth. The job growth rate had been improving from 2009 to 2014 but in 2015 it was lower than in 2014 and it looks like it will be lower in 2016 than in 2015.
Real GDP rose a at an annualized rate of just 0.5 percent in the first quarter due to sharp declines in business investment, trade and a much slower inventory build. A lower inventory build usually means that customer demand is lower.
The Fed is likely to raise interest rates at least once this year, which will help the insurance industry and banks but will hurt elsewhere. An environment of rising rates is a drag on the economy, international sales and the stock market.
By comparison to the rest of the globe, the US is doing better than most countries and regions. The business that make up the S&P 500 derive about 30% of their sales from outside the US, which was a large part of earnings difficulties this quarter.
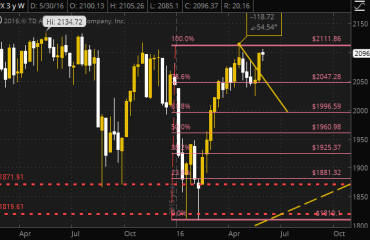
Although the US may not go into a recession, US corporate profits will continue to be weak for the near term. There will continue to be good and bad economic reports to drive the market. The good reports may count more than the bad reports because expectations are so low. Business to business spending will continue to be slow and in-store retail sales will be disappointing. The lows have probably been put in for the markets for 2016 and I doubt that the S&P 500 can make it above 2150 until much later in the year.