The quote, “Try again. Fail again. Fail better,” is often attributed to Samuel Beckett. However, the parody title “Worstward Ho” from 1983 mentions, “Ever tried. Ever failed. No matter. Try again. Fail again. Fail better,” reflecting on those words and connecting to my comments yesterday about one of my biggest losses in USD. This led me to revisit Aristotle (I’m not sure why I’m reading classics now – at other stages of my life, I didn’t enjoy them at all).
Back to the topic, the Greek philosopher Aristotle (384–322 BC) mentioned that flourishing requires balance. One of my natural virtues is clearly money management and partnerships; I love to eliminate conflicts of interest. This is why, when I aim for balance, I keep trying, especially after failing to assemble a balanced portfolio that can reduce volatility, significant drawdowns, and perform similarly to the best historical equity indices. How can I ensure that one of my best qualities is perfectly balanced?
I am reaching the conclusion that the question might be asked wrongly. Balance matters in every aspect, but who can tell me when I need to be angry, I am not too angry… or when the market demands great performance and I need to be brave, I am not too brave? The beauty of portfolio management is that at the end of any period, the trader/market participant receives a performance score, which is the best way to provide a level ground for all to measure success.
This is where grit comes into play. Personally, I always knew or always wanted that during my 40s my career would take off, extending until… my body says stop. Role models like Charlie (Berkshire), Joe (Vanguard), or Ray (Bridgewater) have paved the road.
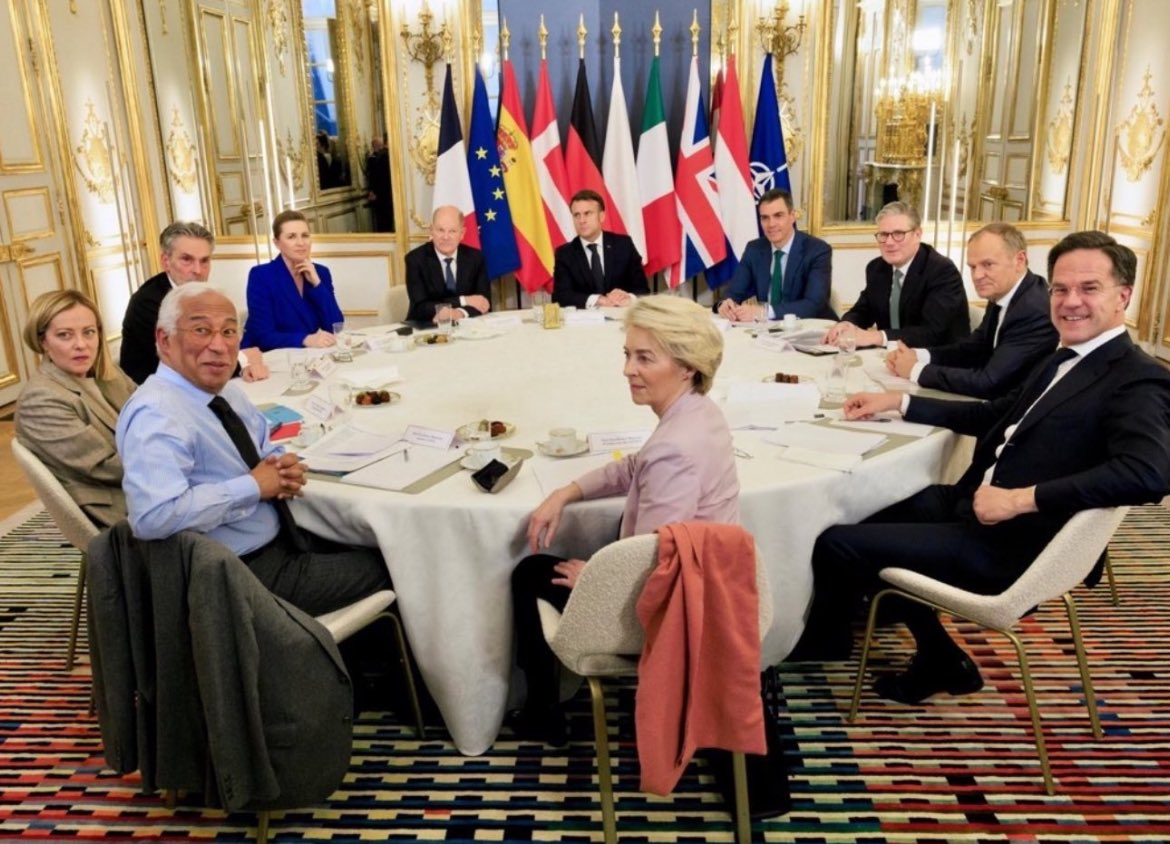
Throughout my investing life, I have been faced with the nuanced and often impossible ethical questions or decisions, and virtue ethics can become our guiding light in complex decision-making. For example, when I constituted arbitrary stop-loss levels at -7%, -12%, and -20%, it clearly overshadowed my financial career. There are newer philosophical theories that are much worse than the classics; for instance, Utilitarianism, which focuses on the consequences of actions rather than the virtues or actions themselves. I totally disagree; the best action is not the one that makes the most people happy. A superb example was yesterday’s European emergency meeting after Trump talked to the French leader.

Highlights were:
- European leaders meet in Paris after Macron speaks with Trump.
- Senior US and Russian officials head for talks in Saudi Arabia.
- Britain says it could send peacekeeping troops to Ukraine.
- Ukraine says it will not recognize talks held without it.
While being a good person is difficult, it’s much more manageable with the help of proper theoretical guidelines. Similarly, while being a good wealth manager is challenging, it becomes easier and more manageable with a proper system that provides a defined edge. This leads to a dependency on that model, which simultaneously provides a sound mechanism for discipline at the cost of one’s reputation.
Overall, utilitarianism fails at critical points. For example, it justifies killing one healthy person to harvest their organs to save the lives of eight others. The solution is a contract.
In 1998, Scanlon published “What We Owe to Each Other,” which, in my investment world, serves as the Prospectus for most Partnerships. This is the ultimate investment contract where the goal is to treat others’ interests as being as important as one’s own. By adhering to the rules of a partnership, this approach sets aside egoistic behaviors and offers a chance to compromise in a way that’s a win-win for both sides.
In this system, both managers and investors grant everyone the ability to veto any rule before we start establishing them. Since unfair rules will be vetoed and rejected, people will naturally design ones that others can accept. If they don’t, the rules simply won’t be implemented. This way, the final norms will be acceptable to everyone and accommodate everyone’s needs equally. The actions and results of the manager can be clearly explained and constrained. Here, the manager is given a structure where selfish behavior is abandoned, with the ultimate goal of fostering trust and harmony.
Investors’ capacity for reason, focused on the common goal of consistent performance, in my case, resolves differences and can help to terminate or expand the investment after each periodic review, which acts as the level ground for all investment performances.
In the end, is just performance that matters? Or the perfect combination with trust and conflict fee endeavor?
Most read news of today
https://x.com/MarioRandholm/status/1891849513855299733

Disclaimer:
“Subscribe to my blog and social media.” Thanks for your comments and support!