

Shares climb as firmer Chinese yuan eases deflation fears We have a shortened week this week due to President’s Day but it will be a busy week. We have Option Expiration this week which always makes things volatile. Economic reports will be light this week for the United States except for Wednesday. Wednesday has
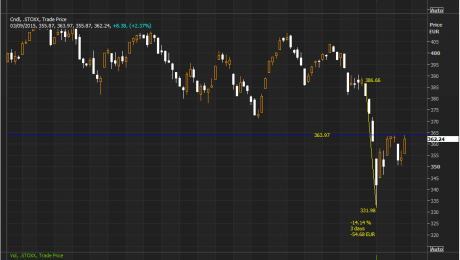
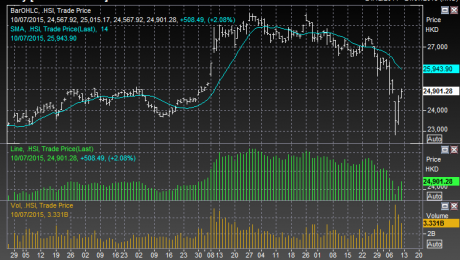
Hang Seng posted three days of expansion reaching again 25000. Wall Street jumped and the euro rallied on optimism that Greece would be able to secure fresh funding at an upcoming weekend meeting, while Treasuries plummeted. Gold traded higher, but pared earlier gains as the Fed signaled a rate hike in this year and
Overnight Shanghai plunged another 5.9%. Now the Shanghai has plunged 32% since mid-June. On the other hand, Greece promised to implement pension and tax reforms as early as next week as the first step to securing a three-year rescue loan to cover debt obligations, according to a letter requesting the funding from European partners on Wednesday.
Here are the update from today: Greece will not pay IMF on Tuesday: Govt official All 10 S&P sectors in the red; deepen losses in afternoon CBOE Volatility index .VIX spikes. Went short volatility Jan 2016. Euro STOXX 50 index – biggest one-day fall since 2011. Tens of thousands rally against bailout ahead of referendum
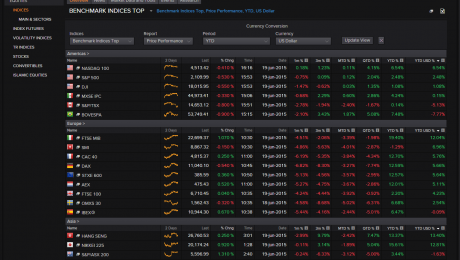
Today Bids for safe-haven assets picked up on worries that Greece is edging toward debt default and pushed the dollar and Treasuries higher, while stocks retreated. Oil slipped on profit-booking and gold declined. Nasdaq, SP500 and Dow positive in the YTD in USD, Most of all the Indexes in EU are positive except SPAIN and in